Quality-Controlled Accounting Outsourcing That Protects Your Bottom Line
Financial errors rarely announce themselves. A miscoded expense sits quietly in the ledger. A supplier bill gets paid twice. A lodgement date slips past during a busy month. Then the auditor asks a question, a client spots a wrong invoice, or a penalty notice arrives, and trust takes a hit that no correcting journal can fully reverse.
That’s why CFOs and firm partners worry about outsourcing finance work. Accuracy and security feel too important to hand over. But the risk sits in weak controls, not in where the work is done. Quality-controlled accounting outsourcing, built on strong accounting internal controls, layered review, and audit-ready processes, can make your finance function more resilient, not less.
- 32% of occupational frauds happened where internal controls were missing.
- Late US tax returns can draw penalties of 5% per month, up to 25%.
- Brand-safe finance rests on layered review, data security, and audit-ready records.
- Dedicated Philippine accountants cost 50 to 70% less than local hires.
The Hidden Cost of Financial Errors
Small accounting errors become big problems when nobody catches them early.
Ledger Errors Compound
One wrong coding rule can misstate every transaction it touches. Unreconciled accounts hide duplicate payments and missing receipts. By year-end, the clean-up costs more than the original work, and management decisions have been made on numbers that weren’t right.
Missed Deadlines Carry Penalties
Tax authorities don’t accept busy season as an excuse. In the US, the IRS failure-to-file penalty is 5% of unpaid tax for each month a return is late, up to 25%. Similar regimes apply to BAS in Australia and VAT in the UK, and for accounting firms, a missed client deadline also damages the relationship.
Weak Controls Invite Fraud
The ACFE’s Occupational Fraud 2024 report, based on 1,921 cases, found a lack of internal controls contributed to 32% of frauds, and override of existing controls to another 19%. Controls only protect you when they exist and are enforced.
Data Entry vs Financial Governance
Comparing hourly rates misses what actually protects your numbers. The real difference lies in how work is reviewed, controlled, and documented.
| Cheap Data Entry | Quality-Controlled Governance |
|---|---|
| Transactions keyed, rarely checked | Secondary review before sign-off |
| Shared logins and downloaded files | MFA, role-based access, data kept in your cloud |
| Coding by guesswork | Trained on your chart of accounts and coding rules |
| Payments released by whoever processes them | Approvals and payment release stay with you |
| Close whenever it’s done | Fixed month-end close checklist and schedule |
Governance as Brand Protection
Accurate invoices protect customer relationships. On-time lodgements protect your standing with regulators. Clean audit trails protect your credibility with lenders, investors, and auditors. For a finance function, quality control isn’t overhead. It’s reputation management.

Three Pillars of Brand-Safe Accounting
Accurate, secure finance operations rest on three disciplines working together.
Layered Review
- Secondary reviewer checks
- Daily bank reconciliations
- Accuracy reporting
- Supervised first close
Data Security
- Multi-factor authentication
- Role-based permissions
- Data kept in your software
- Signed confidentiality agreements
Audit Readiness
- Documented transaction trails
- Accurate AP and AR ageing
- Balance sheet reconciliations
- On-time month-end close
Multi-Tiered Review and Accuracy Audits
Every piece of work moves through defined checkpoints. Transactions are coded to your rules, bank and credit card accounts are reconciled, and a second reviewer checks the output before it reaches your finance lead. Regular quality checks and accuracy reporting show where errors occur, so processes improve over time.
Data Security and Privacy Compliance
Your team works inside your own cloud accounting systems with multi-factor authentication and role-based permissions, so financial data stays in your software rather than on local devices. Every team member signs confidentiality agreements, and processes follow the Philippine Data Privacy Act of 2012 alongside your obligations under the Australian Privacy Act or UK GDPR.
Keep the keys. Your offshore team prepares bills, payment batches, and journals, but approvals, payment releases, and bank authority stay with you. Approval limits are set in your software permissions from day one.
Audit-Ready Financial Reporting
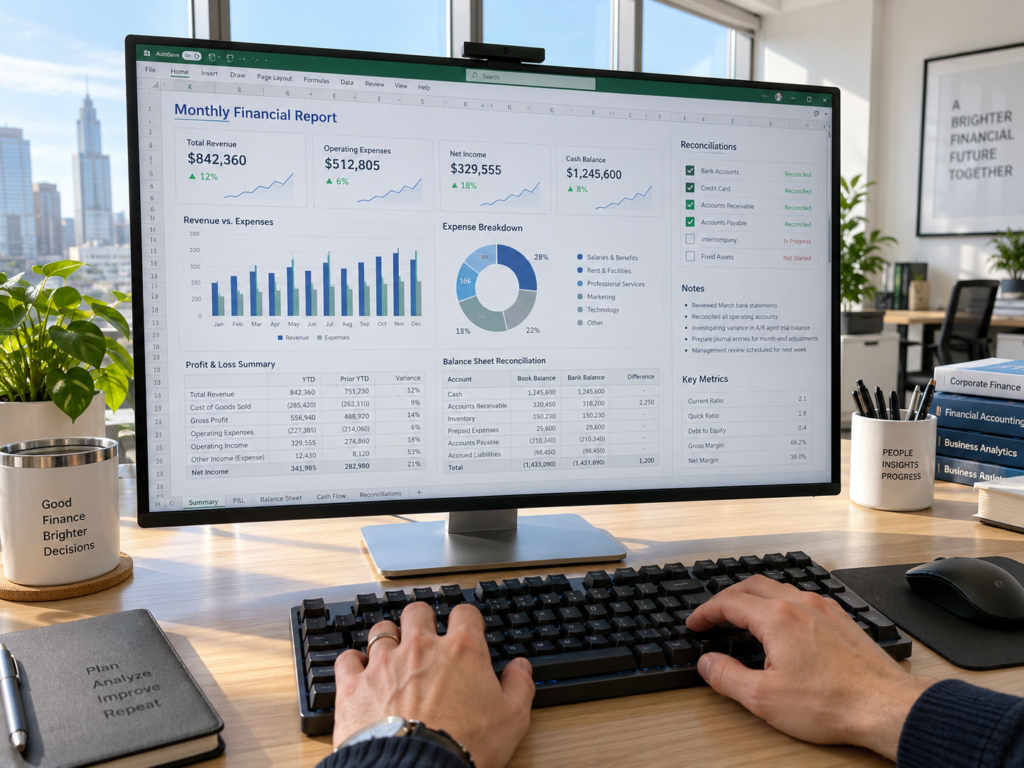
A structured month-end close process produces management accounts, P&L, balance sheet, and cash flow reports on a fixed schedule. A typical month-end close checklist looks like this:
| Close Step | Control Outcome |
|---|---|
| Bank and card reconciliations | Every transaction matched and explained |
| AP and AR review | Accurate ageing and no duplicate bills |
| Accruals, prepayments, and journals | Supporting documents attached to every entry |
| Balance sheet reconciliations | Balances tied to source records |
| Management reporting | Budget vs actual and KPI commentary |
“Clients never see your ledger. They see the invoice, the statement, and the deadline you did or didn’t meet.”
Segregation of Duties by Design
Segregation of duties is one of the simplest and strongest accounting controls. An offshore model makes it easier to enforce, because preparation and approval naturally sit with different people.
| Your Offshore Team Prepares | Your Team Approves |
|---|---|
| Supplier bills and payment runs | Payment approval and release |
| Reconciliations and journals | Review and sign-off |
| BAS, VAT, and sales tax workpapers | Lodgement by your registered agent |
| Year-end workpapers and drafts | Partner or controller review |
Controls That Catch Errors Early
These everyday financial controls stop small mistakes before they reach your reports, your clients, or your auditors.
Frequent Bank Recs
Daily or weekly matching keeps errors fresh and easy to fix.
Duplicate Checks
Bills checked by supplier, amount, and reference.
Supplier Validation
Bank detail changes confirmed through a known contact.
Coding Rules
Documented rules for every recurring transaction.
Variance Analysis
Unusual movements flagged and explained monthly.
Locked Periods
Closed months protected from later changes.

An Extension of Your Finance Team
UpraisIT accountants and bookkeepers work exclusively on your account, inside your existing cloud ecosystem, following your processes, approval limits, and month-end checklist.
Your team is trained on the platforms you already use, including:
- Xero
- MYOB
- QuickBooks Online
- NetSuite
- Sage
- FreeAgent
- Dext
- Hubdoc
- Gusto
- Bill.com
Built for Every Jurisdiction
Philippine accounting standards are based on IFRS, which also underpins Australian and UK reporting. Team members are trained on GST, BAS, and Single Touch Payroll for Australia, VAT and Making Tax Digital for the UK, and US GAAP, sales tax, and 1099 requirements for the US.
Capacity for CPA Firms
For accounting practices, CPA firm outsourcing adds white-label staff who prepare year-end workpapers, financial statements, and tax return drafts for partner review. Firms can scale ahead of EOFY, year-end, or tax season with two to three weeks’ notice.
Why UpraisIT
Tested Before They Touch Your Books
Philippine accountants are degree-qualified, and many hold the local CPA licence. Every candidate passes:
- A technical accounting test
- A software assessment for your platform
- An English assessment and background check
- Your interview before anyone joins
Quality Built Into Go-Live
Your team is trained on your chart of accounts, coding rules, and approval limits before touching live data. Go-live starts with a supervised first close, followed by regular quality checks, accuracy reporting, and monthly reviews with your finance lead.
Hours That Fit Your Close
| Your Location | Typical Setup |
|---|---|
| 🇦🇺 Eastern Australia | Day shift sharing most of your working day |
| 🇦🇺 Perth | Same time zone, full overlap |
| 🇬🇧 United Kingdom | Evening shift overlapping your working day |
| 🇺🇸 United States | Night shift or overnight processing |
Explore further. See UpraisIT’s accounting and bookkeeping outsourcing, offshore back office solutions, or how offshore staffing works.

Frequently Asked Questions
Common questions from CFOs, controllers, and CPA firm partners about quality-controlled accounting outsourcing.
Your team works inside your own systems with multi-factor authentication and role-based access, so data stays in your cloud software. Every team member signs confidentiality agreements, and processes follow the Philippine Data Privacy Act alongside your local privacy obligations.
Always. Your team prepares bills, payment batches, and journals, but approvals, payment releases, and bank authority stay with you, reflected in your software permissions.
The team prepares workpapers and draft returns, and your registered tax or BAS agent, accountant, or in-house team reviews and lodges them. This keeps you compliant with ATO, HMRC, and IRS rules on who can lodge and sign off.
Yes. White-label staff prepare year-end workpapers, financial statements, and tax return drafts for your review, helping your firm take on more clients through busy season.
Most Australian, UK, and US clients save 50 to 70% compared with a local hire. You pay one flat monthly rate per team member covering salary, benefits, equipment, secure workspace, and account management.
Your financial integrity is part of your brand. With layered review, segregation of duties, secure access, and a disciplined month-end close, a dedicated offshore finance team keeps your ledgers accurate, your deadlines met, and your reputation intact.
Accurate books. Strong controls. Protected reputation.
Book a Financial Controls Assessment
Share your software, transaction volumes, and reporting deadlines with UpraisIT. We’ll map which work can move offshore safely and design a quality-controlled finance team around your internal controls.
Schedule Your Assessment → No commitment. Response within 1 business day.